Inventory Carrying Cost: Formula and Annual Worksheet
Build an inventory carrying-cost worksheet with capital, storage, service and loss assumptions. Calculate the annual rate without double counting.
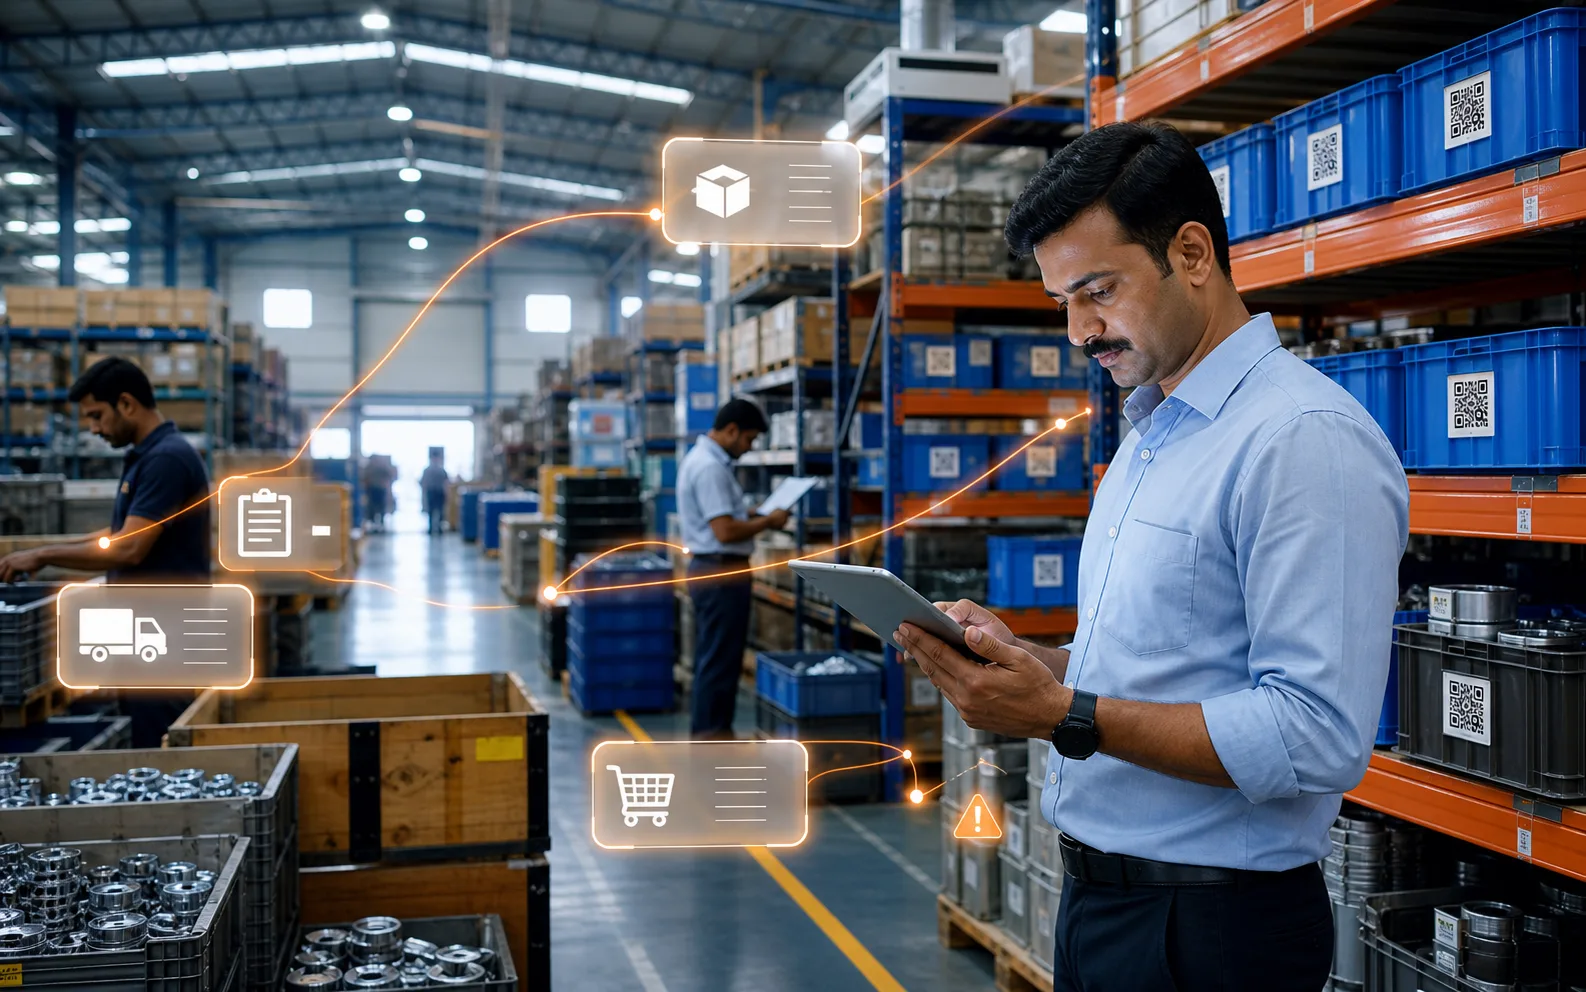
Inventory carrying cost is the cost of holding stock over a stated period. For an annual management estimate, divide the selected annual holding costs by average inventory value for the same year and express the result as a percentage.
Holding costs can include space, insurance, handling, expected inventory losses and a capital charge for funds tied up in stock. Your worksheet should show which amounts are actual expenses, which are allocations and which are planning assumptions. That distinction determines what can change when you reduce stock.
Build the annual worksheet
| Component | Annual amount | Basis to document |
|---|---|---|
| Capital charge | ₹1,00,000 | Approved planning rate applied to average stock value; an assumption, not necessarily a cash expense |
| Attributable storage | ₹60,000 | Inventory share of space and related costs; state the allocation rule |
| Insurance and holding-related handling | ₹20,000 | Separate invoices or allocated costs not already included above |
| Expected inventory loss | ₹20,000 | Supported damage/obsolescence assumption; exclude duplicate charges |
| Total selected holding costs | ₹2,00,000 | Sum of these non-overlapping categories |
With an average inventory value of ₹10,00,000, the annual carrying-cost rate is ₹2,00,000 ÷ ₹10,00,000 × 100 = 20%. These figures are illustrative. They are not a benchmark for every manufacturer.
Use a consistent valuation basis for the denominator. A single year-end stock value can distort the rate when demand is seasonal or large receipts arrive near the close. The average inventory guide explains when several dated observations are more useful than an opening-and-closing average.
Avoid counting the same cost twice
If warehouse rent is included in the storage line, do not add it again through a broad overhead percentage. If the capital charge already represents the selected cost of funds, do not automatically add a second charge for the same funding. Keep the treatment agreed with finance visible in the worksheet.
Separate expected risk from realised losses when constructing a budget. For example, including both an expected annual obsolescence allowance and the same loss as a separate cost would inflate the total. Record the reporting purpose and the period before choosing either measure.
This management estimate is different from the inventory value recognised in financial statements. The IAS 2 summary describes inventory cost within its accounting framework. A cost included in a holding-cost decision worksheet is not automatically eligible to be capitalised into inventory.
Test what a lower stock balance would change
Reducing average stock can reduce the assumed capital charge while leaving leased warehouse rent unchanged. Handling cost may fall, stay flat or rise if deliveries become more frequent. Identify the cost driver for each line before treating an estimated reduction as a cash saving.
For one item family, compare current average value, ageing, required buffer, supplier lead time and order frequency. Then change one assumption and recalculate. Check service levels and shortage risk alongside the holding-cost estimate. The storage-policy example shows why fewer pallet positions do not automatically mean lower rent.
Use Optiwise records to support the review
Optiwise connects stock movement and ageing with purchasing and production demand. Review slow-moving items, min/max levels and existing supply before raising another requirement. Smart Suggest checks BOM demand against stock, open purchases and ongoing production so the buying decision retains its material context.
Questions from manufacturing teams
Is a 20% carrying-cost rate standard?
No. It is the result of this example. Your rate depends on the selected costs, average stock value, period and financing or risk assumptions.
Should I use month-end stock as average inventory?
Use observations that represent the period. One month-end figure may be misleading if stock fluctuates substantially. State the averaging method.
Will cutting stock reduce warehouse rent?
Only if the space reduction changes a charge you actually pay. A fixed lease may remain unchanged even when the warehouse has more free space.
Bring an item-family stock report to an Optiwise demo and follow its ageing, demand and replenishment records.
Related Posts
Steel Receipts in Sheets, Square Metres and Kilograms
Reconcile sheet count, nominal area and actual weight on one steel receipt. Keep conversion assumptions and supplier discrepancies visible before release.
7 Nov 2026Read more →Keep the Heat Number With Every Cut Bar Piece
Keep cut billets and reusable bar ends linked to their heat certificate. Follow the physical ID, job issue and missing-mark decision in Optiwise.
1 Nov 2026Read more →AI in Procurement: What Changes in Your Daily Work
Use Optiwise to compare supplier offers and follow the selected quote into a purchase order, while keeping delivery, quality and approval decisions clear.
14 Jun 2026Read more →Cloud Procurement | Optiwise
Learn cloud procurement for SMEs and manufacturers, including purchase requests, approvals, supplier follow-up, inventory linkage, and how AICAN Optiwise improves control.
12 Jun 2026Read more →